
You want to know how to move to Portugal without losing a year to paperwork. The route is well mapped. Pick your profile, line up your visa, get your fiscal number, then decide whether you rent first or buy.
Portugal has different routes depending on your passport. EU/EEA/Swiss citizens have free-movement rights and do not need a visa. Many UK and US movers use a residence-visa route before relocating, though other residence routes and exemptions may apply. A visa-free tourist stay is not a residence permit. Buying property does not grant residence.
This guide covers the full sequence, with 2026 figures you can use for planning. Costs and requirements can change, so confirm them with the relevant authorities before you make decisions.
1. Who can move to Portugal in 2026
Portugal applies three different rulebooks depending on your passport. Find yours before you read anything else.
EU/EEA/Swiss citizens - free movement. An EU citizen moving to Portugal skips the visa queue entirely. You travel with an ID card or passport, then register with the Câmara Municipal of your area within 30 days of completing your first three months in the country. The document you receive is the CRUE (Certificado de Registo de Cidadão da União Europeia). After five consecutive years of legal residence you can request a permanent residence certificate from AIMA, a separate document, not a CRUE renewal.
UK citizens - post-Brexit route. Since Brexit, UK citizens are third-country nationals. A passport allows a short visa-free visit, generally 90 days in any 180-day period, but that is tourism rather than residence. Many people moving from the UK follow a residence-visa route through the Portuguese consulate before relocating, then apply for a residence permit after arrival. If you were already resident in Portugal by 31 December 2020, your rights may instead fall under the Withdrawal Agreement; check the correct residence document for your case.
US and other non-EU citizens. Many third-country nationals moving from the USA use a residence visa obtained through the Portuguese consulate before relocating, followed by a residence-permit application after arrival. The route depends on each person’s circumstances and applicable exemptions. Buying a house does not grant residence.
| Profile | Visa before travel on a standard route | Registration after arrival |
|---|---|---|
| EU/EEA/Swiss | No | CRUE at the Câmara Municipal |
| UK — moving to Portugal from the UK | Yes - residence visa | Residence permit at AIMA |
| US / non-EU | Yes - residence visa | Residence permit at AIMA |
Documents do not translate themselves, and consulates do not chase you. Start preparing several months before your target arrival; this is a planning estimate, not a processing guarantee.
Planning to buy property after your move? Request a free mortgage comparison.
2. Visas by profile: D7 retirement, D8 digital nomad, D2 entrepreneur
D7, D8 and D2 are common residence-visa routes for people moving to Portugal. All are national (type D) visas issued by the consulate for your place of residence.
D7 - passive income and retirement. For retirees, pensioners and anyone living on stable passive income such as pensions, rents, dividends or royalties. Active remote work is generally considered under the D8 route. The 2026 income benchmark is €920 per month, or €11,040 per year, for the main applicant - that is Portugal's national minimum wage. The reference rises by 50% for a second adult (€460/month) and 30% per dependent child (€276/month). A couple therefore needs €1,380/month; a couple with one child needs €1,656/month. Treat those as the floor, not a guarantee: consulates want regular, documented income, and may ask for 12 months of evidence. Confirm the current checklist with your consulate before applying.
D8 - digital nomad and remote work. For people working remotely for a foreign employer or their own foreign clients. In 2026 the threshold is €3,680 per month - four times the national minimum wage. Applicants normally show income from the three months preceding the application. The D8 has a higher income threshold than the D7 and may suit tech, design, consulting and online-business profiles.
D2 - entrepreneur and self-employed. For people starting or running a business in Portugal. There is no fixed legal minimum investment; the authorities assess whether your business is viable and adequately funded, not whether it clears a number. Personal means are a separate requirement, referenced at €920/month - €11,040 for 12 months. A business plan is strongly recommended, even where it is not strictly required: product, Portuguese market, your experience, start-up costs, funding sources, realistic revenue projections, timeline.
Golden Visa - investors. Still open in 2026, but real estate no longer qualifies for new applications. The live route runs through a qualifying fund from €500,000, with a minimum five-year maturity and at least 60% invested in Portuguese-headquartered companies. Investment risk applies. Most movers do not need this route.
Visa eligibility and required documents depend on your circumstances and can change. Confirm your route and current checklist with the Portuguese consulate or a qualified immigration professional.
3. Documents you need before you move: NIF, bank account, health insurance
This is the unglamorous block that decides whether your move happens on schedule. Get these three first - everything else unlocks from them.
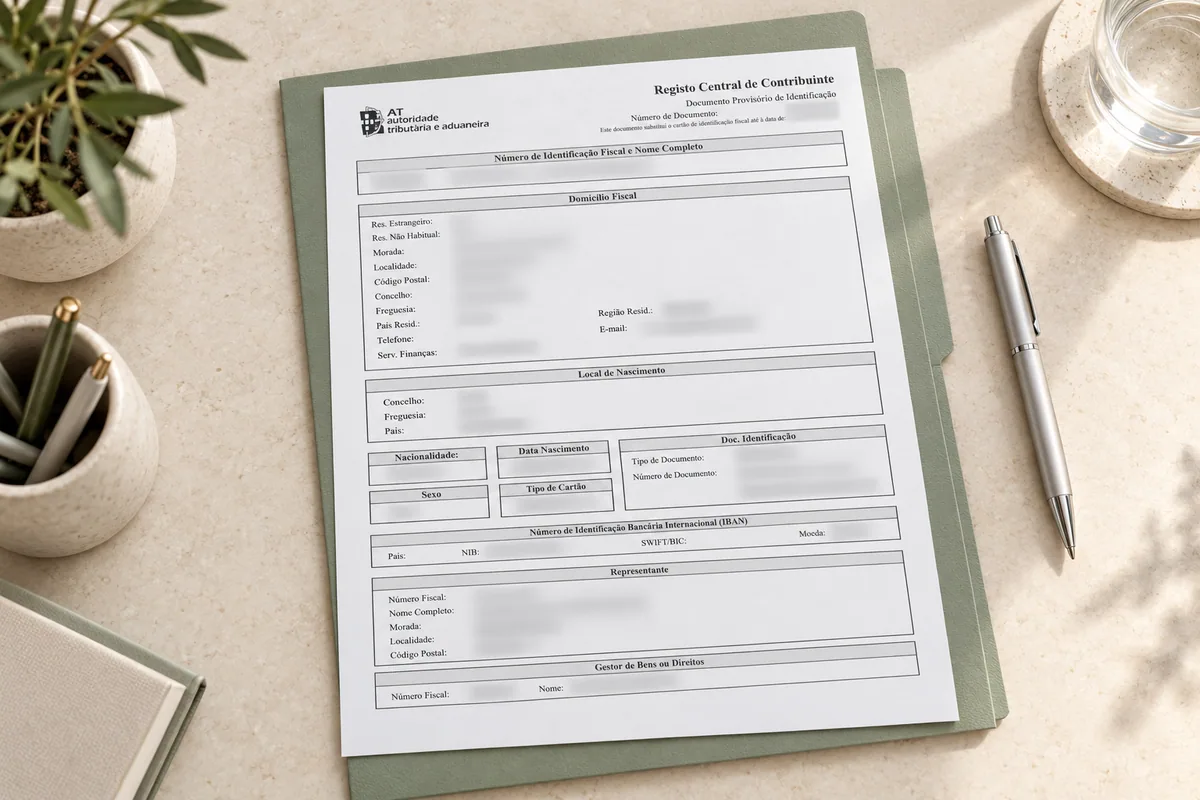
NIF - your Portuguese tax number. No NIF, no bank account, no property purchase, no utility contract, no lease with a registered landlord. Non-residents can obtain one through a representative holding a power of attorney (procuração), submitted online via the Tax Authority's e-balcão service or in person at a tax office. Prepare a passport copy, proof of address abroad, the power of attorney (signature generally certified, waived when the representative is a lawyer or solicitor acting as such), and the representative's ID. If that person will also act as your tax representative, the power of attorney must say so explicitly.
Portuguese bank account. Needed for the visa application in most cases, for the mortgage later, and for direct debits. You will be asked for your NIF, passport, proof of address and, depending on the bank, proof of income. Opening remotely is possible at several banks - ask before you travel.
Health insurance. Private cover is required for most residence visas and is what most expats keep thereafter. Budget €30–€150 per month for one adult with a local Portuguese plan. Basic plans start around €13–€20/month; a mid-tier plan for a 40-year-old with outpatient cover runs about €70–€77/month. International expat plans start around €85/month and climb steeply with comprehensive worldwide cover. Check waiting periods, co-payments and pre-existing conditions before you sign.
Also in the folder:
- Apostilled birth and marriage certificates, with certified translations.
- Criminal record certificate from your country of residence (usually valid 3 months).
- Proof of accommodation in Portugal - a lease or a property deed.
- Proof of income for the last 3–12 months, and bank statements.
- Passport valid for at least 3 months beyond your planned stay, and 2 blank pages.
Two more documents matter for Americans relocating to Portugal specifically: your US tax filings stay alive after the move, so set up your filing path before departure (more in section 7). For UK movers, check your driving licence exchange options and pet travel rules early - both are handled before departure, not after.
4. What moving to Portugal actually costs
Budget the move, then budget the first six months. Most disappointment comes from skipping the second step.
| Item | 2026 planning figure |
|---|---|
| National residence visa (D7/D8/D2) | ~€110 per applicant, plus any visa-centre service fee |
| AIMA residence permit | €247.30 standard (€133 reception and analysis + €114.30 grant); where an online application is available, the 25% reduction brings these fees to €185.60 total |
| Household shipping (US origin, 20-foot container) | $2,500–$10,000+ |
| Private health insurance | €30–€150 per month, per adult |
| Total direct relocation cost, one person or couple | ~$6,000–$16,000 before living costs |
Then the ongoing side. A one-bedroom in Lisbon rents for roughly €1,067–€1,419 per month depending on whether you are outside or inside the centre; a room in a shared flat runs €300–€550. A single expat should budget €1,900–€2,500 per month for rent plus typical living expenses; a couple sharing a one-bedroom, €2,650–€3,350. Porto, Braga, Coimbra and the Alentejo all come in lower than Lisbon.
Visa and AIMA charges are per applicant. Multiply by everybody in the family. And note that these are planning estimates, not quotes - shipping in particular swings with volume, season and destination.
5. Housing: rent first or buy straight away
For many first-time movers, renting for 6–12 months before buying can make it easier to assess a neighbourhood in person. School runs, commutes, noise and a building’s condition are difficult to judge from a listing. The right choice depends on your plans, finances and familiarity with the area.
Renting first. Expect a 2-month deposit plus the first month's rent, a Portuguese guarantor or a bank guarantee at many landlords, and a registered lease (contrato de arrendamento) that you should insist on - it is your proof of address, your visa support and your tax paperwork.
Buying straight away. This can make sense if you know the area, the property fits your longer-term needs, and you have enough cash for the deposit, taxes and a reserve. Mortgage pre-approval is conditional. Before signing the promissory purchase and sale contract (CPCV), have an independent lawyer or solicitador review it and advise whether a financing-refusal protection clause is appropriate for your situation. Purchase taxes apply from the transaction:
- IMT (property transfer tax) depends on a property's value and use, its location and your tax residence. Estimate it with our IMT calculator.
- Stamp duty is generally 0.8% of the same taxable value as IMT (the purchase price or property tax value, whichever is higher), plus 0.6% of the loan amount for mortgage terms of five years or more. Exemptions may apply; notary and registration fees are also payable.
- Annual IMI on the property's tax value, and AIMI at the higher end of the market.
- Buyers aged 35 or under: age alone is not enough to qualify for IMT Jovem relief. First-acquisition, permanent-home, tax-status and property-value conditions apply; confirm eligibility with a tax adviser.
IMT depends on a property's value and use, its location and your tax residence. Use our IMT calculator for an estimate, then read our guide to buying property in Portugal. Our calculator includes the non-resident IMT rate; ask your tax adviser to confirm any exemptions or refund eligibility.
Non-resident residential purchases. Under Article 17 of Portugal’s CIMT, a residential property acquired by a non-resident is generally subject to a flat 7.5% IMT rate unless a statutory exception applies. A buyer who becomes Portuguese tax resident within two years may be eligible to request a refund of the difference by applying within six months of becoming resident. A separate capped-rent exception may also apply. Confirm eligibility and evidence with a Portuguese tax adviser.
Common choices for people moving from the US, UK or EU include an apartment in Lisbon or Porto, a house in Cascais or Sintra, or a lower-cost base inland or in the Algarve. Location often has a bigger effect on the budget than nationality.
Our take
Buying before you move can work when you already know the area and the property suits your longer-term plans. Keep enough cash for the deposit, taxes, purchase costs and an emergency reserve. Get mortgage pre-approval and independent legal checks before you commit.
6. Financing: mortgage conditions for non-residents
Non-resident buyers often need a larger deposit than residents. Confirm your likely loan-to-value (LTV) with a lender before you start viewing properties.
Loan-to-value. Non-resident mortgages generally offer 70–80% LTV, depending on the bank and borrower profile. Plan for a 20–30% deposit against the purchase price, plus taxes and fees. You may need more cash if the valuation is below the purchase price or the lender finances less. Banks calculate the loan against the lower of the purchase price or the bank's valuation.
How mortgage rates are quoted. Portuguese variable-rate mortgages generally combine a Euribor reference rate with a bank spread. Fixed and mixed offers vary by lender and may depend on bundled products such as salary domiciliation, insurance or a packaged account. Check each bank’s current non-resident terms and compare the full cost, including products and fees, before choosing.
What the bank will ask for: NIF, passport, proof of address, income evidence (payslips or tax returns, translated where needed), bank statements, existing debts, and proof of funds for the deposit and fees. Foreign income is normal for us; we know which lenders price it best.
CAFIMO compares options from 15+ partner banks, so you can review multiple offers side by side. Read our non-resident mortgage guide and learn about our mortgage service in Portugal. When you are ready to discuss financing, request a free mortgage comparison.
7. Tax and residency: NHR vs IFICI
Residency is not a passport stamp. It is a tax status, and Portugal decides yours on facts.
The 183-day rule. Spend more than 183 days in Portugal in the relevant 12-month period and you are generally tax-resident. Portugal can also treat you as resident if you keep a habitual residence here. Residents are taxed on worldwide income.
NHR is closed to new arrivals. The original Non-Habitual Resident regime - the 20% flat rate that pulled in a decade of expats - no longer accepts new applicants. Its successor is IFICI, sometimes called NHR 2.0.
IFICI in practice. A 20% flat IRS rate on Portuguese employment or self-employment income from a qualifying activity, for up to 10 consecutive years. Qualifying activities are narrow: higher-education teaching and research, certified start-ups, R&D roles at recognised centres, specified highly qualified professions (certain engineers, scientists, physicians, professors, ICT specialists), roles in investment-incentive companies or exporters meeting a turnover threshold, plus Madeira and Azores incentives. Many routes require a PhD, or a degree plus at least three years' experience. Foreign-source income is largely exempt - but foreign pensions are not covered, which matters enormously to D7 retirees. Eligibility depends on the employer and the actual role, not the job title. Compare both regimes in our NHR guide.
US citizens: check ongoing tax filings. The US–Portugal treaty can reduce double taxation, but it does not automatically exempt US citizens from US tax. US citizens generally remain subject to tax on worldwide income; whether a federal return is required depends on filing thresholds and personal circumstances. Available relief may include the Foreign Tax Credit or, for qualifying earned income, the Foreign Earned Income Exclusion. Separate reporting rules may also apply:
- FBAR (FinCEN Form 114) when the combined maximum value of foreign accounts exceeds $10,000 at any point in the year.
- Form 8938 (FATCA) may be required above applicable thresholds. For eligible taxpayers living abroad, the thresholds are generally $200,000 at year-end or $300,000 at any time for single filers, and $400,000 / $600,000 for married couples filing jointly; different thresholds apply to people living in the United States. Married taxpayers filing separately use the single-filer thresholds for taxpayers living abroad.
FBAR and 8938 overlap but are distinct obligations. Get cross-border advice before you move if you hold investments, pensions or a business.
UK movers: the Portugal–UK double taxation treaty governs pensions and income. Check your state pension position and whether voluntary National Insurance contributions make sense before you leave.
8. Your step-by-step checklist
Use this as a planning checklist and adapt it to your passport, residence route and personal circumstances.
- Choose your visa route - D7, D8, D2, or none if you hold an EU passport. Confirm the thresholds with your consulate for the current year.
- Get your NIF - remotely via a representative with power of attorney, or on arrival.
- Open a Portuguese bank account - needed for the visa file and everything after.
- Book private health insurance - €30–€150/month for a working-age adult.
- Collect and apostille your documents - birth, marriage, criminal record, income proof, all translated.
- Apply for the visa at the consulate - allow 4–6 months from first document to boarding pass.
- Secure initial housing - a registered lease or a short-term base for the first months.
- Travel and register - EU citizens at the Câmara Municipal; visa holders book AIMA for the residence permit (€247.30 standard).
- Get a NISS and complete any tax or Social Security registration that applies when you start working or become self-employed.
- Decide rent or buy - and if you buy, run the IMT and stamp duty numbers first.
- Line up financing early - budget around 6–10 weeks from the lender's receipt of a complete file to purchase and loan signing; this is an estimate, not a promise.
- Fix your tax status - 183-day count, IFICI eligibility if relevant, and your home-country filing obligations.
How long does the whole process take?
Four to eight months can be a planning range for non-EU movers to prepare documents, apply for a visa and arrive. AIMA appointments and residence-permit processing can extend the timeline. EU citizens skip the visa stage but may need to register after the first three months.
Can I move to Portugal before I have a visa?
A visa-free visit does not grant residence or a general right to work. Under a standard D7, D8 or D2 route, the visa is normally obtained before relocating, but other residence routes and exemptions may apply. A lease by itself does not confer residence. Confirm your route with the Portuguese consulate or a qualified immigration professional.
Do I need to buy property to get residency?
No. Residency comes from a visa route, not a deed. Real estate no longer qualifies for the Golden Visa either.
How much do I need to put down as a non-resident buyer?
Plan for a 20–30% deposit against the purchase price, plus taxes and fees. You may need more if the valuation is below the purchase price or your lender finances less.
Before you commit to a property, get your financing numbers in writing. CAFIMO compares offers from 15+ banks at no cost to you. Request a free mortgage comparison.
Official sources
- AIMA - registration certificate for EU citizens
- AIMA - updated fees table effective 1 March 2026
- Portuguese Ministry of Foreign Affairs - residence visa requirements
- Portugal’s national minimum wage
- Official visa-fee regulation, Portaria 91/2025
- GOV.UK - Living in Portugal
- Portuguese Tax Authority - IMT rates
- Portuguese Tax Authority - applying for a NIF
- PwC Portugal - 2026 Property Transfer Tax guide
- PwC Portugal - IFICI / NHR 2.0
- novobanco - mortgages for non-resident foreigners
- BPI - solutions for non-resident foreigners
- IRS - comparison of Form 8938 and FBAR requirements
Figures reflect 2026 published rates and estimates. Visa thresholds, taxes and mortgage pricing change - confirm every number with the competent authority or your adviser before committing.