
Buying property in Portugal is open to foreigners of any nationality - no residence permit, no minimum investment, no local partner required. You need a Portuguese tax number (NIF), a clear view of the purchase costs and a reliable way to make payment. A Portuguese bank account is useful and commonly used for mortgage financing, but it is not a universal legal condition for a cash purchase (gov.pt purchase guide).
This 2026 guide to buying property in Portugal for foreigners covers the whole picture: the process, the taxes in force since the new housing law, financing for residents and non-residents, and the pitfalls that cost buyers the most. So, can foreigners buy property in Portugal? Yes. Here is how to do it without losing money on the way.
The numbers first: the average sale price in Portugal reached €2,337 per m² in the second quarter of 2026, up 16.5% year on year (INE data). Growth is slowing, but prices are not falling. Read this before you sign anything.
Buying a House in Portugal (Key Takeaways)
- Any nationality can buy. EU, UK, US, Brazilian or Swiss - the rules on ownership are the same. Only your tax residency changes your tax bill.
- Four steps to the deed: get a NIF, find the property, sign the CPCV, pay the sinal (a reservation deposit deducted from the price at the deed), and sign the escritura.
- Budget roughly 4% to 10% of the purchase price for acquisition taxes and closing costs. The exact amount depends on tax residency, property use, value, VPT and financing. This estimate excludes the deposit and optional legal advice.
- Non-resident buyers pay a flat 7.5% IMT on urban residential property from 25 May 2026, subject to the statutory cancellation conditions.
- Financing: up to 90% LTV for a permanent home, up to 80% for a second home or rental, up to 80% for non-residents at most banks.
- Buying property does not grant residency. Portugal's Golden Visa stopped accepting real estate in October 2023. D7, D8 and D2 are the routes that still work.
- CAFIMO compares 15+ banks and gets approvals in under 30 days after the initial submission. Our service is 100% free for the client.
Get a free mortgage simulation
How Does The House-Buying Process Work in Portugal?
Buying a home in Portugal as a foreigner follows four steps. None of them is complicated. All of them are easier when financing is already in place.
1. Prepare Yourself: Get a Portuguese Tax Number
The NIF is your fiscal identity in Portugal. You need it to open a bank account, sign a deed, pay a utility bill or register a property.
Anyone can request one before leaving home, either directly at a Finanças office or through a fiscal representative. If you live outside the EU/EEA, you generally need a Portuguese tax representative unless you register for the Tax Authority’s official electronic-notification service. A passport or civil identity document is normally used; a residence permit is not a prerequisite.
2. Find Your Dream Home: Where to Look For
Three routes, and they are not exclusive:
- Online platforms - the fastest way to size the market. Most listings sit on Imovirtual, Idealista and OLX.
- Real estate agencies - they charge 3% to 6%, indexed to the sale price and usually paid by the seller. They bring you off-market properties and visit them on your behalf.
- Buyer's agents - independent professionals who hunt across several agencies, useful for tailored searches and negotiations.
Financing capability matters at this stage. A bank pre-approval tells you your real budget and strengthens your offer. It also protects your deposit later.
3. Make an Offer: Signing the CPCV
Once you agree on price, you sign the Contrato de Promessa de Compra e Venda (CPCV) and pay the sinal - a reservation deposit usually around 10% of the price, held by the seller and deducted from the amount due at the deed.
The CPCV is legally binding. If you withdraw without a valid reason, you risk losing the deposit. If you need a mortgage, have the CPCV reviewed and include a suspensive clause for mortgage refusal with a clear deadline and the required evidence. A low bank valuation alone should not be presented as an automatic right to a refund.
A lawyer is optional in Portugal, but independent legal advice is useful for checking ownership, licences, debts, planning restrictions and the CPCV. Any lawyer’s fee is separate from the cost examples and percentages below.
4. Sign The Final Deed: The Escritura
The escritura transfers ownership. All documents are sent to the notary in advance: your NIF, identity document and CPCV, plus proof of funds and mortgage documents where applicable; the property certificate, tax record, use licence and energy certificate on the seller's side.
Two practical rules for 2026:
- IMT and Stamp Duty are paid on the day of the deed. Have the funds ready.
- Check the VPT before calculating IMT and purchase Stamp Duty. In the usual case, the taxable base is the higher of the value stated in the deed or contract and the VPT (official Tax Authority guidance). The examples below use the purchase price shown in the calculator screenshots. A VPT above the purchase price is uncommon in a normal arm’s-length sale, but if it applies, it raises the taxable base and tax due.
Once the deed is signed, the notary registers the sale and you become the owner.
Financing a Property in Portugal as a Foreigner
Mortgage is the part where sequencing decides everything. Get pre-approval before you sign a CPCV, not after.
For purchases with bank financing, allow around 45–60 days from mortgage application to deed. The timing depends on your file, document readiness, the bank’s processing, valuation and notary availability.
CAFIMO has taken more than 2,000 clients to the deed, financed over half a billion euros and built a network of 15+ banking partners. That reach shows up in three numbers:
- 80% average financing rate of the purchase price
- Under 30 days from initial submission to bank approval for the fastest files
- 100% free broker service, at any purchase amount
Portuguese Financing Characteristics
- Up to 90% financing for a permanent home
- Up to 80% financing for a second home or rental investment
- Up to 80% financing for non-residents in many cases; some situations are limited to 70%.
- A maximum term of 40 years may be available for a resident’s permanent home, subject to age limits and bank policy. Non-resident mortgages are generally capped at 30 years.
- As indicative September 2026 figures, fixed rates start from 2.20% and variable rates from 2.48%. Variable rates combine 6- or 12-month Euribor with a bank spread, typically 0.5% to 1%; fixed rates are priced separately and often use average government bond yields as a reference. The offer depends on the borrower, products and bank.
- Debt-to-income is generally capped at 45% of net monthly income, subject to the lender’s assessment and applicable rules.
- Life insurance and multi-risk home insurance, which you can place inside the bank or outside it with CAFIMO
Buying Property in Portugal as a Non-Resident: Rules, LTV and Taxes
Buying property in Portugal non resident is routine - a large share of the loans we place go to clients who do not live in the country. The key point: banks and the Tax Authority look at tax residency, not nationality.
Financing rules
- Up to 80% LTV at many banks, which means a 20% deposit. The bank normally calculates financing against the lower of the purchase price and its valuation.
- Some situations are limited to 70% LTV, depending on the borrower, income, property and bank.
- Foreign income is accepted. Expect 3 to 6 months of payslips, tax returns, an employment contract or company accounts.
- For a variable-rate loan, the interest rate combines 6- or 12-month Euribor with the bank’s spread, indicatively 0.5% to 1% depending on the borrower and bank. A fixed rate is priced separately and is often based on average government bond yields rather than Euribor plus a spread.
Tax rules
- IMT at a flat 7.5% on urban residential property, in force since 25 May 2026. No progressive brackets, no permanent-home exemption, and the same rate for EU and non-EU buyers.
- The difference can be cancelled if you become a Portuguese tax resident within two years of the purchase, or if you let the property at a moderate rent - lease signed within 6 months, kept for at least 36 months in the first 5 years, rent capped at €2,300 per month in 2026. The request must be filed within 6 months of the qualifying event (rules and exemptions).
- IMI and AIMI work exactly as for residents. IMI runs at 0.3% to 0.45% of the property's tax value; AIMI applies above €600,000 for individuals and €1.2 million for couples filing jointly (PwC guide).
- On a future sale, 50% of an eligible capital gain is included in taxable income and taxed at progressive IRS rates; this treatment also applies to non-residents under the rules in force since 2023.
- If you rent the property out, you file an annual IRS return in Portugal.
Should I Choose a Portuguese or Foreign Bank?
Banks based outside Portugal rarely lend directly against a property in Portugal. If a lender does not operate locally, it may ask you to provide collateral on an asset in your home country. Portuguese banks can register a mortgage locally, which is why most of the files we handle use Portuguese lenders.
Buying a House in Portugal (Costs)
Buying a house costs more than the listing price. As a practical guide, budget roughly 4% to 10% of the purchase price for acquisition taxes and closing costs, depending on residency, use, financing and property value. This excludes the down payment and optional legal fees. The examples below separate resident and non-resident cases for the same €200,000 property:
| Cost | Resident, €200,000 primary home | Non-resident, €200,000 secondary home or rental |
|---|---|---|
| Buyer contribution (not a fee) | €20,000 (90% LTV) | €40,000 (80% LTV) |
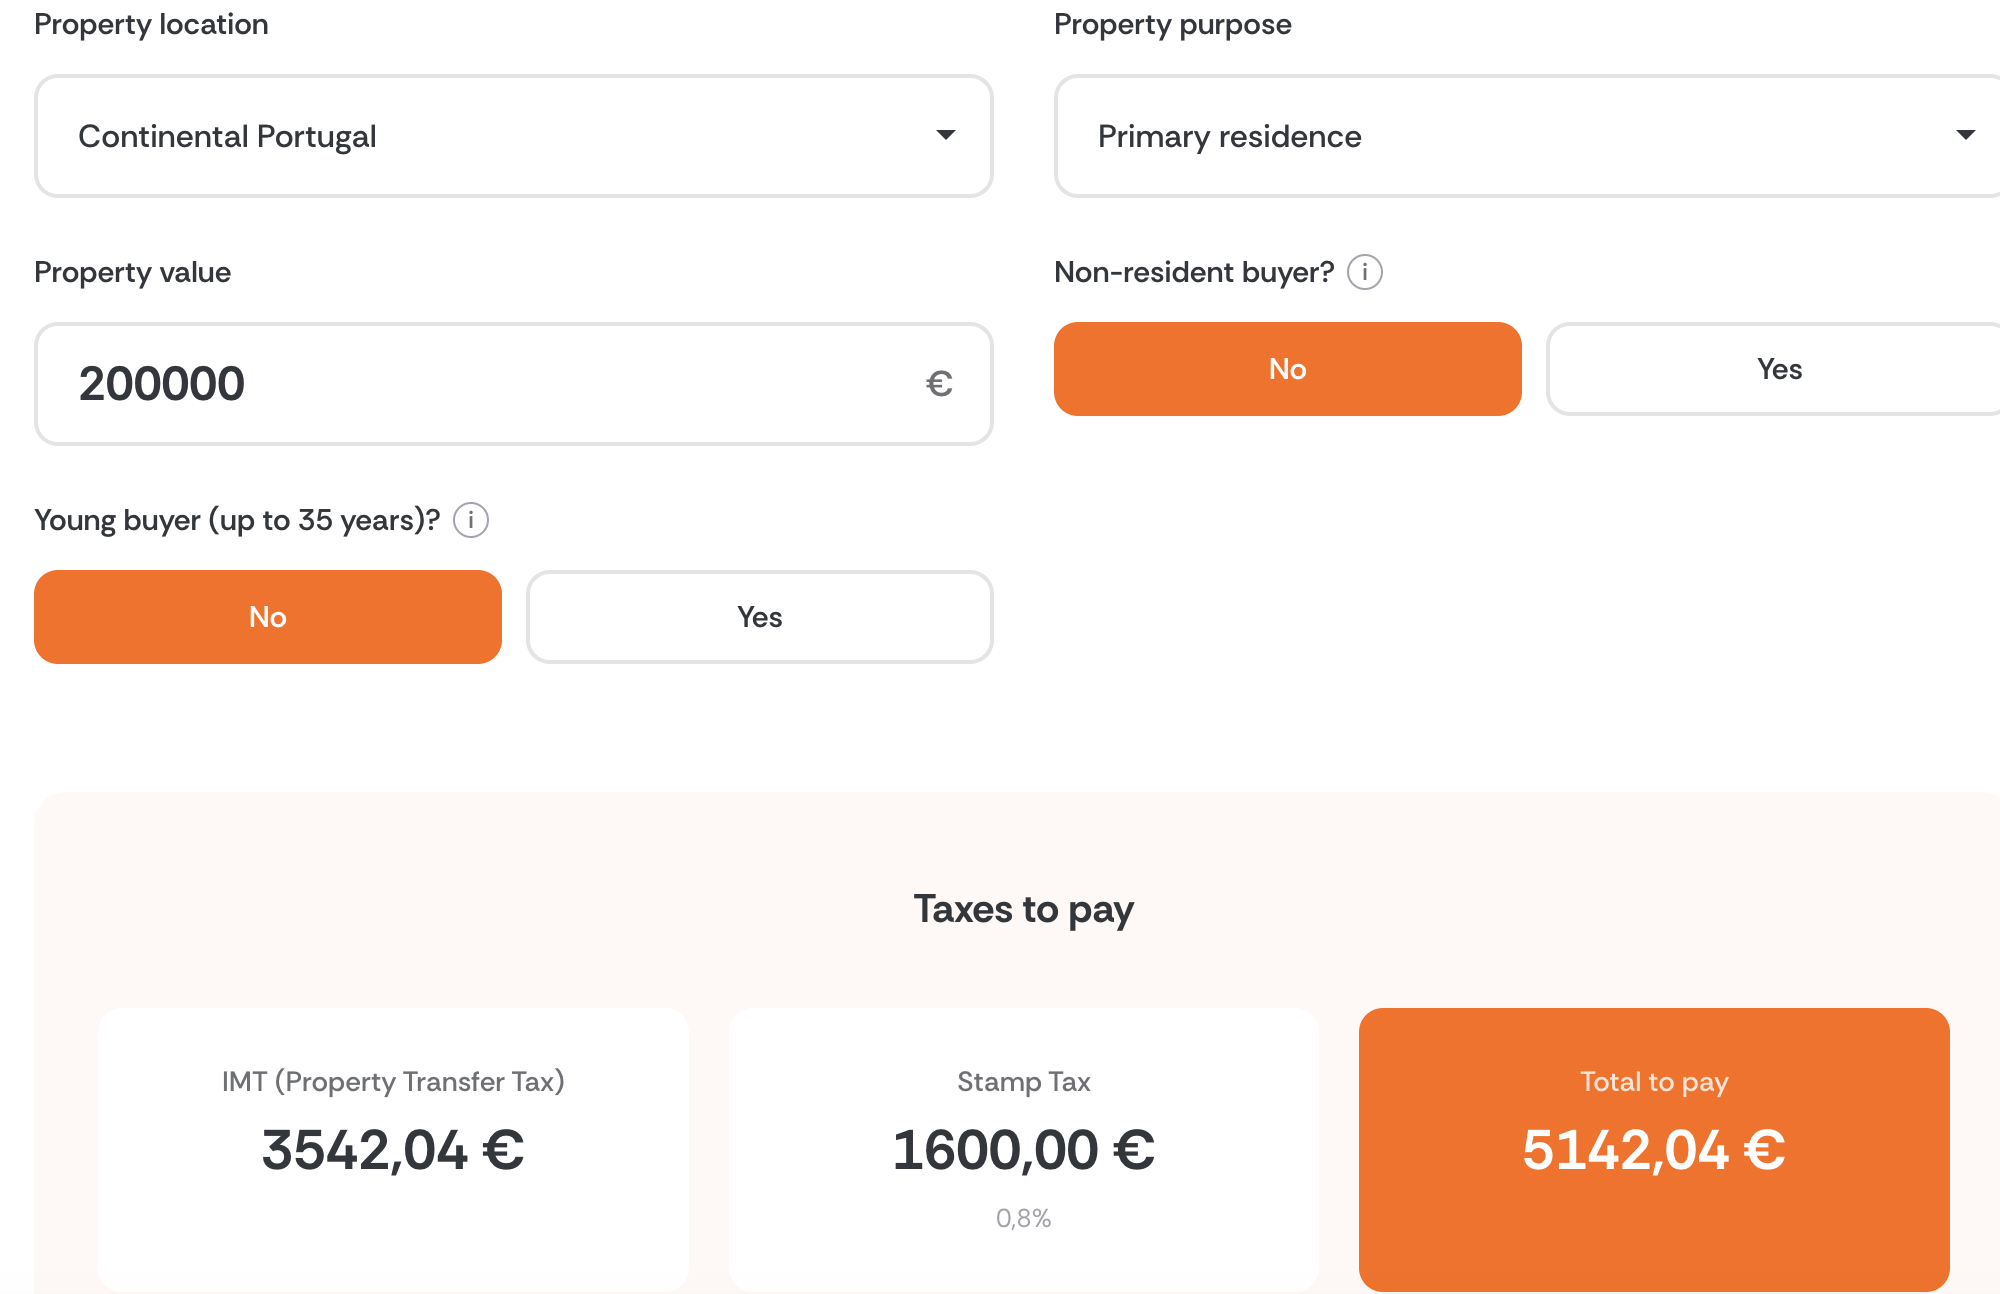
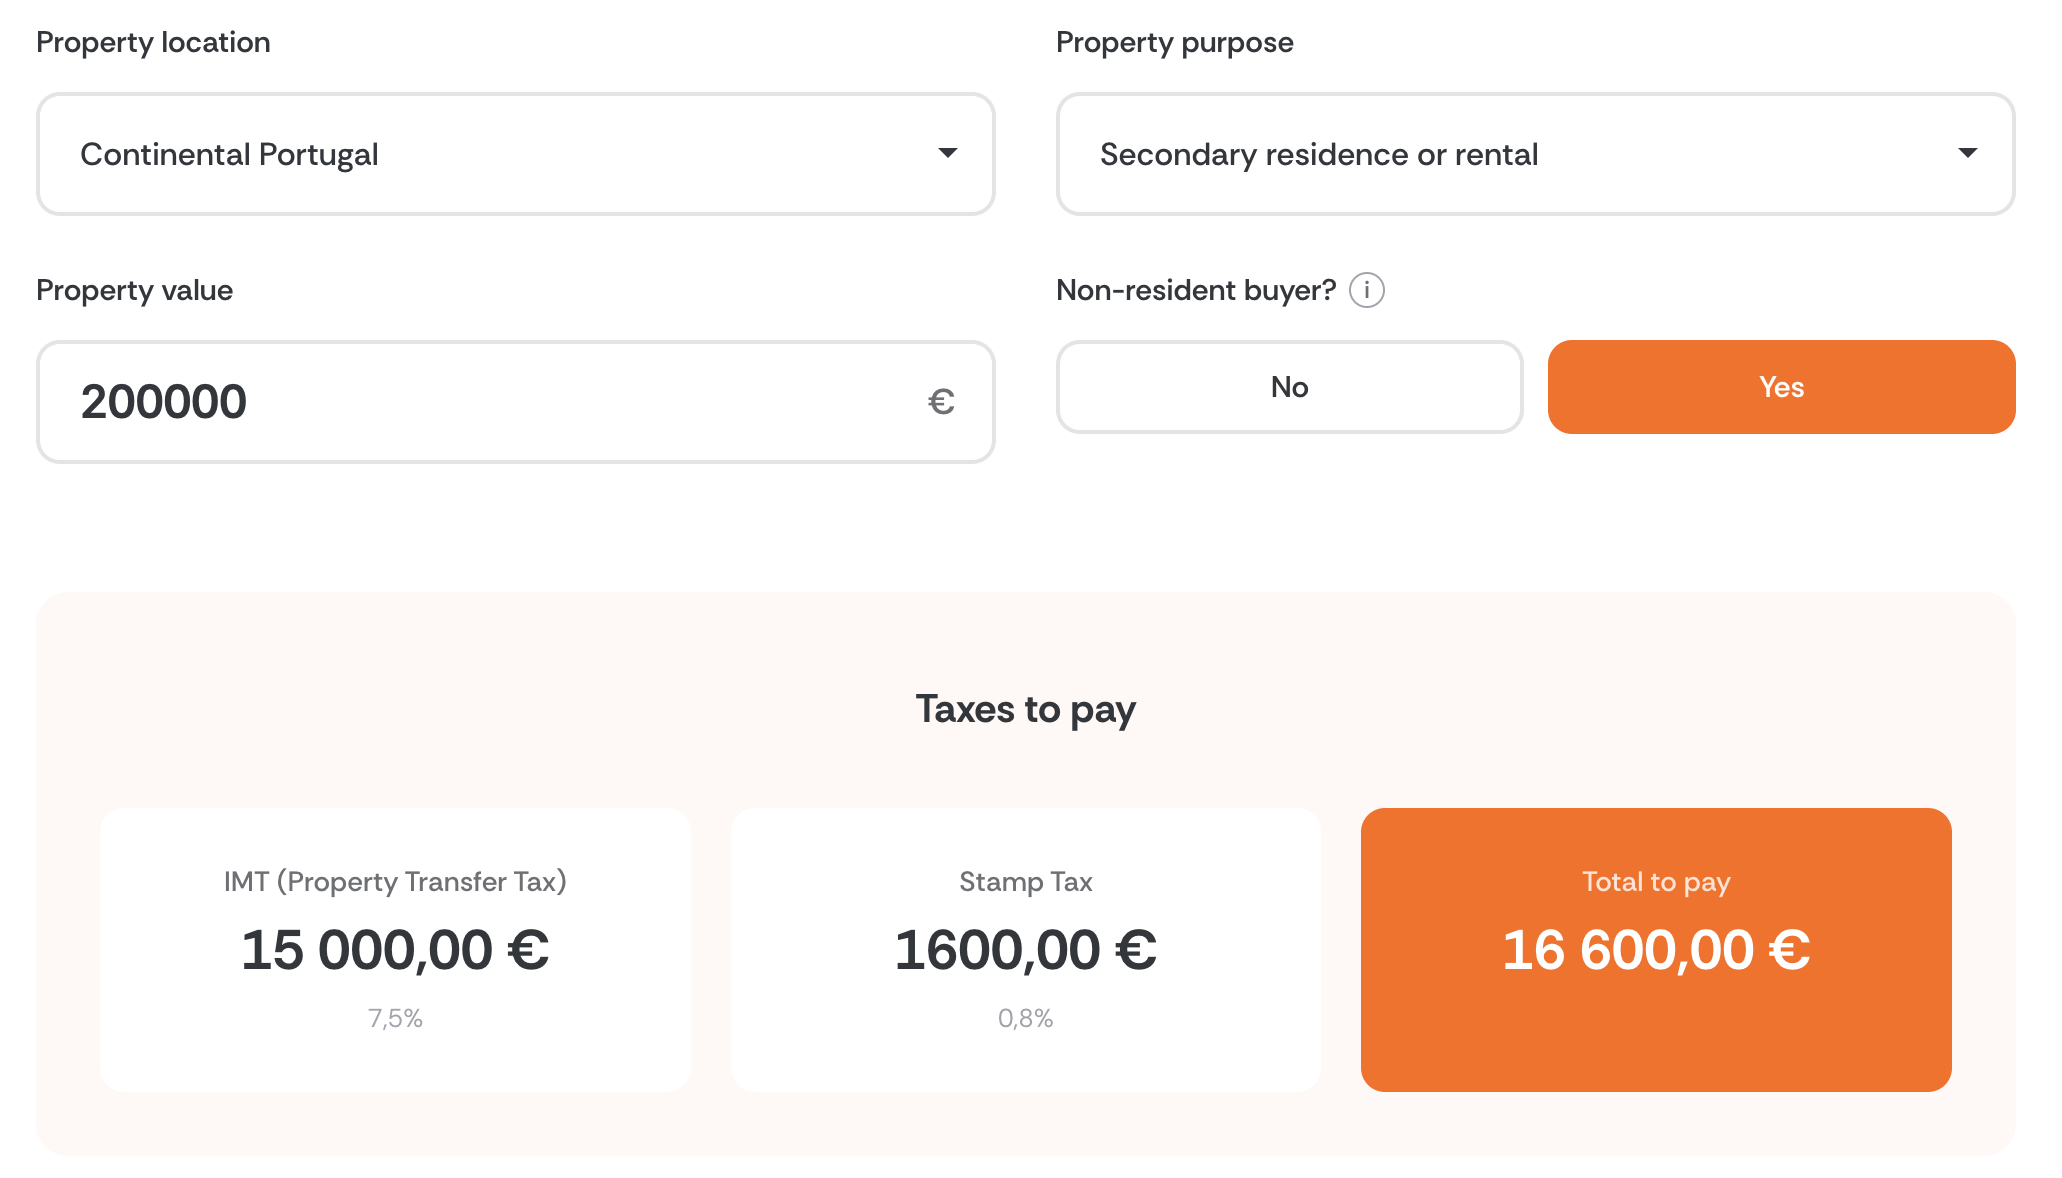
| IMT | €3,542.04 | €15,000 (7.5% flat rate) |
| Purchase Stamp Duty (0.8%) | €1,600 | €1,600 |
| Loan Stamp Duty (0.6%; only if financed) | €1,080 (loan of €180,000) | €960 (loan of €160,000) |
| Bank, notary and registration costs | ≈ €2,000 | ≈ €2,000 |
| Total buyer funds through completion, including deposit | €28,222 | €59,560 |
The calculator screenshots show €5,142.04 in purchase taxes for a resident buying a €200,000 primary home and €16,600 for a non-resident buying a €200,000 second home or rental property. Adding the approximately €2,000 bank/notary costs gives €7,142.04 and €18,600 respectively, before any loan Stamp Duty. In the financed examples above, the 0.6% loan Stamp Duty adds €1,080 or €960. The total-funds figures include the buyer contribution (deposit), which is usually paid earlier at the CPCV and is not a fee. Both IMT and purchase Stamp Duty normally use the higher of the contract value and the VPT; a VPT above the price is uncommon in a normal arm’s-length sale (Portuguese Tax Authority guidance).
Tax and Acquisition Costs
IMT 2026 (Imposto Municipal sobre as Transmissões Onerosas de Imóveis) depends on the property location and use, buyer’s tax residency, and taxable value. The taxable base is generally the higher of the deed or contract value and the VPT; a VPT above the purchase price is uncommon in a normal arm’s-length sale. The scenarios above were generated with our IMT simulator; you can use it to estimate the tax for your own situation. Eligible tax-resident buyers aged 35 or under may qualify for full IMT and purchase Stamp Duty relief on a first permanent home up to €330,539, with reduced rates above that threshold, subject to statutory conditions.
- Purchase Stamp Duty (IS) - 0.8% of the taxable acquisition value used for IMT (normally the higher of the deed/contract value and VPT).
- Loan Stamp Duty (ISUC) - 0.6% of the loan amount, only when the purchase is financed by credit. It does not apply to a cash purchase.
- IMI - annual municipal tax of 0.3% to 0.45% of the property's tax value.
- AIMI - additional tax above €600,000 of property value for individuals.
- Lawyer - optional, but recommended for independent due diligence. Fees vary and are not included in the percentages or examples above.
- Bank, notary and registration costs - approximately €2,000 combined, based on the examples provided.
The 2026 housing tax package also introduced a 10% IRS rate on qualifying residential rents until 2029 and relief for qualifying capital gains reinvested into moderate-rent housing. See the official Tax Authority information.
Maintenance Costs
An empty property still costs money. Owners' condominium fees, insurance, IMI and repairs do not pause when you are abroad.
- Budget 1% of the property value per year for upkeep, plus condominium charges.
- Property management fees run at 10% to 20% of the rent if you delegate lettings and maintenance.
- Self-managing saves the fee and costs you travel, coordination and time.
Not happy with all of these additional costs? There are none on our side. CAFIMO's broker service is 100% free, whatever the amount of your purchase.
Insurance For Buying A House In Portugal As A Foreigner
Two covers matter when you buy with a mortgage.
- Property insurance (seguro multirriscos) - protects the building and its contents against fire, water damage, theft and natural events. Fire insurance is legally required for each unit in a building under horizontal property, such as an apartment condominium (ASF guidance); mortgage lenders may also require property cover. Check the exact requirements for your home and loan. Expect €120 to €300 per year for a T2 or T3 apartment in a city, and €350 to €600 for a detached house. Wider cover with theft and electrical damage goes above €500 (market comparison).
- Mortgage life insurance (seguro de vida) - required by most lenders to cover the outstanding loan in the event of death or qualifying disability. There is no reliable universal price range: the premium depends on the loan amount, the borrowers’ age and health, and the coverage selected.
You are not obliged to buy either policy from the bank granting the loan. Placing life insurance outside the bank is one of the simplest ways to lower the total cost of a mortgage - same cover, different price.
Why Buy a House in Portugal? (9 Key Reasons)
Portugal keeps attracting international buyers for reasons that did not change with the tax rules.
- Rental demand and yields. Gross yields sit around 5.3% in mainland Portugal, with Porto at 4.9%, Lisbon at 4.1% and the Algarve at 4.0% in the 12 months to March 2026 (yield report). Long-term lets are the lower-risk engine; short-term lets pay more where a licence is available.
- Tax on gains. Only 50% of a capital gain is taxed, at progressive rates, for residents and non-residents alike.
- Quality of life. Climate, coastline, healthcare and a slower rhythm at a fraction of Northern European prices.
- Culture and history. From fado to azulejos, Portugal has an identity that does not need a translator.
- Cost of living. Still below most of Western Europe, even after the price rises of the last five years.
- Safety. Portugal ranks 7th in the Global Peace Index 2026, with a score of 1.427 (Global Peace Index).
- A tax regime for newcomers - but not the old one. The Non-Habitual Resident (NHR) regime is closed to new applicants since 2024. It was replaced by IFICI, which grants a 20% flat rate on qualifying Portuguese income and, in many cases, exemption on foreign income for 10 years - but only for research, innovation and other designated high-value roles (IFICI explained). Anyone still selling you NHR as an available option is working from outdated information.
- Connectivity. Direct flights to most European capitals, and Lisbon three hours from London, five from New York.
- Prices. Entry-level prices in inland Portugal and the Azores are among the lowest in Western Europe, even as Lisbon and the Algarve sit at the top of the national scale.
Buying a Second Home in Portugal: What Changes
Buying a second home in Portugal - or buying a vacation home in Portugal for part of the year - changes four things.
- Financing. Expect 80% LTV maximum: a 20% deposit, plus costs. If you are a non-resident, the flat 7.5% IMT applies.
- Short-term letting. Alojamento Local requires a municipal registration. In Lisbon, new registrations are suspended in parishes where short-term lets exceed 2.5% of local housing, with containment rules above 5% and a near-block above 10% (Lisbon AL rules). Check the parish before you buy for Airbnb income.
- Long-term letting. Renting at a moderate rate can both lower your tax and, for non-residents, unlock the IMT cancellation described above - a 10% IRS rate on qualifying rents applies until 2029.
- Running costs. Management fees of 10% to 20%, non-resident tax returns, and AIMI above €600,000 of property value. Budget them before you fall for the view.
The Algarve, the Silver Coast, Comporta and Madeira remain the most liquid second-home markets.
Overview of the Real Estate Market in Portugal
The market is still growing, but the gear has changed.
- Closed transaction prices: average of €2,337 per m² in Q2 2026, +16.5% year on year - a slowdown from +19.8% in the first quarter, with 6.4% fewer transactions.
- Bank valuations: appraisals hit a record high in August 2026, confirming that credit is chasing the same limited stock (valuation data).
- Asking prices: €3,210 per m² nationally in July 2026, per Idealista's price report.
- Macro backdrop: the Public Finance Council revised 2026 GDP growth up to 2.2%, and Fitch upgraded Portugal to A with a stable outlook in September 2026 (Council forecast).
- Policy: the 2026 housing package cut VAT on construction to 6%, exempted capital gains reinvested into moderate-rent housing, and tightened the tax treatment of non-resident buyers.
What Shapes Property Prices in Portugal?
- Location - coastal and metropolitan areas carry a premium; inland Portugal does not.
- Condition and energy rating - A-rated and renovated homes sell faster and finance better.
- Amenities - parking, lift, pool, garden and sea views move prices by double digits.
- Legal status - an unlicensed extension can knock more off the value than the work itself costs.
What Does the Future Hold?
- Growth continues, at a slower pace. Supply is still short of demand in Lisbon, Porto and the Algarve.
- The tax regime now matters more than the mortgage rate. For non-residents, the 7.5% IMT is the single biggest variable in the purchase budget.
- Quality beats speculation. Rental yields in prime city centres are settling near 4%; secondary regions and long-term letting pay more.
Where To Buy a Home in Portugal? Top Picks For Foreigners
Choosing the right location is the highest-impact decision you will make - more than the rate, more than the negotiation.
Lisbon
Lisbon is the deepest and most expensive market in the country, with asking prices around €6,107 per m² in the city in June 2026. Alfama and the historic centre trade on charm; Parque das Nações trades on comfort and transport. Rental licensing is restrictive, so check the parish rules before buying to let.
Pros: jobs, international schools, liquidity. Cons: prices, congestion, tourist pressure.
Porto
Porto sits about €3,309 per m², roughly half of Lisbon. Foz draws families and beach lovers, Bonfim and Campanhã still offer value, and the tech and tourism sectors keep demand steady.
Pros: lower entry price, walkable centre, strong rental demand. Cons: rain, rising prices in the historic centre.
Algarve
The Algarve has the largest concentration of international buyers and asking prices near €4,165 per m² as a region, with Faro at about €3,885 per m². Year-round sun, an established expat community and the strongest seasonal rental demand in Portugal.
Pros: climate, rentals, community. Cons: seasonality, thin local job market.
Silver Coast
From Ericeira to Nazaré, the Silver Coast offers first-rate seaside property at prices Lisbon left behind a decade ago, one hour from the capital. Ideal for retirees and remote workers who want the ocean without the crowd.
Pros: value, proximity to Lisbon, growing infrastructure. Cons: colder winters, fewer services.
Alentejo
Plains, vineyards and rural properties at the lowest prices in the country. Rural tourism and remote work are slowly rebuilding demand around Évora and Comporta's hinterland.
Pros: space, prices, tranquillity. Cons: weak job market, limited infrastructure.
Madeira
Madeira is no longer the cheap island. INE data now places it among the most expensive regions in Portugal, driven by limited supply and sustained foreign demand. Funchal remains the most liquid point of entry.
Pros: year-round mild climate, low crime, international community. Cons: island logistics, import-dependent prices.
Azores
Nine islands, volcanic landscapes and the lowest property prices of any Portuguese region - with the least infrastructure and the slowest resale market.
Pros: affordable, unspoiled, quiet. Cons: remoteness, limited services.
Cost-Comparison For Portuguese Cities
| Location | Average asking price per m² (2026) | Why buyers look here |
|---|---|---|
| Lisbon (city) | €6,107 | Jobs, schools, deepest resale market |
| Cascais | ≈ €5,000 – €5,500 | Families, coastline, 25 minutes from Lisbon |
| Algarve (region) | €4,165 | Tourism income, climate, international community |
| Faro | €3,885 | Airport, hospitals, Algarve capital |
| Lagos | €3,801 | Historic centre, beaches, rental demand |
| Porto | €3,309 | Value, tech and tourism growth |
| Portugal (asking prices) | €3,210 | National average |
| Portugal (closed sales, INE) | €2,337 | Actual registered transactions |
Asking prices and closed prices never match. Use the second column when you build your budget.
Renting vs. Buying in Portugal: Which One's Best?
Rents moved faster than prices. The median one-bedroom flat now costs €1,128 per month nationally and €1,409 in Lisbon (rental data).
Put the two sides together. A €180,000 loan at 3% over 30 years costs about €759 per month before insurance and IMI. The same profile of buyer renting in Lisbon pays nearly twice that, with nothing to show for it at the end.
Buying wins on long horizons, and loses on flexibility. Three factors should drive your decision:
- How long you plan to stay. Under three years, renting usually wins on total cost.
- Income stability and relocation risk. A mortgage is a 30-year commitment to a monthly payment.
- Rates and prices in your target area. Fix a rate if you need certainty; stay variable if you can absorb movement.
For investors, the yield map matters more than the headline price:
| Market | Gross yield (to March 2026) |
|---|---|
| Mainland Portugal | 5.3% |
| Porto | 4.9% |
| Lisbon | 4.1% |
| Algarve | 4.0% |
Building Your Own Home in Portugal
Buying land and building later is a different route from buying a completed home, but the land purchase still incurs IMT and purchase Stamp Duty. The total project also includes design, licensing and construction time.
Costs in 2026:
- €950 to €1,500 per m² for standard construction
- €1,450 to €1,850 per m² for a turnkey, A-rated family house with finishes
- Above €1,800 per m² for high-end projects, and considerably more for luxury builds
- A 100 m² house: €95,000 to €150,000 construction-only, €145,000 to €185,000 turnkey, before land, taxes and site-specific costs
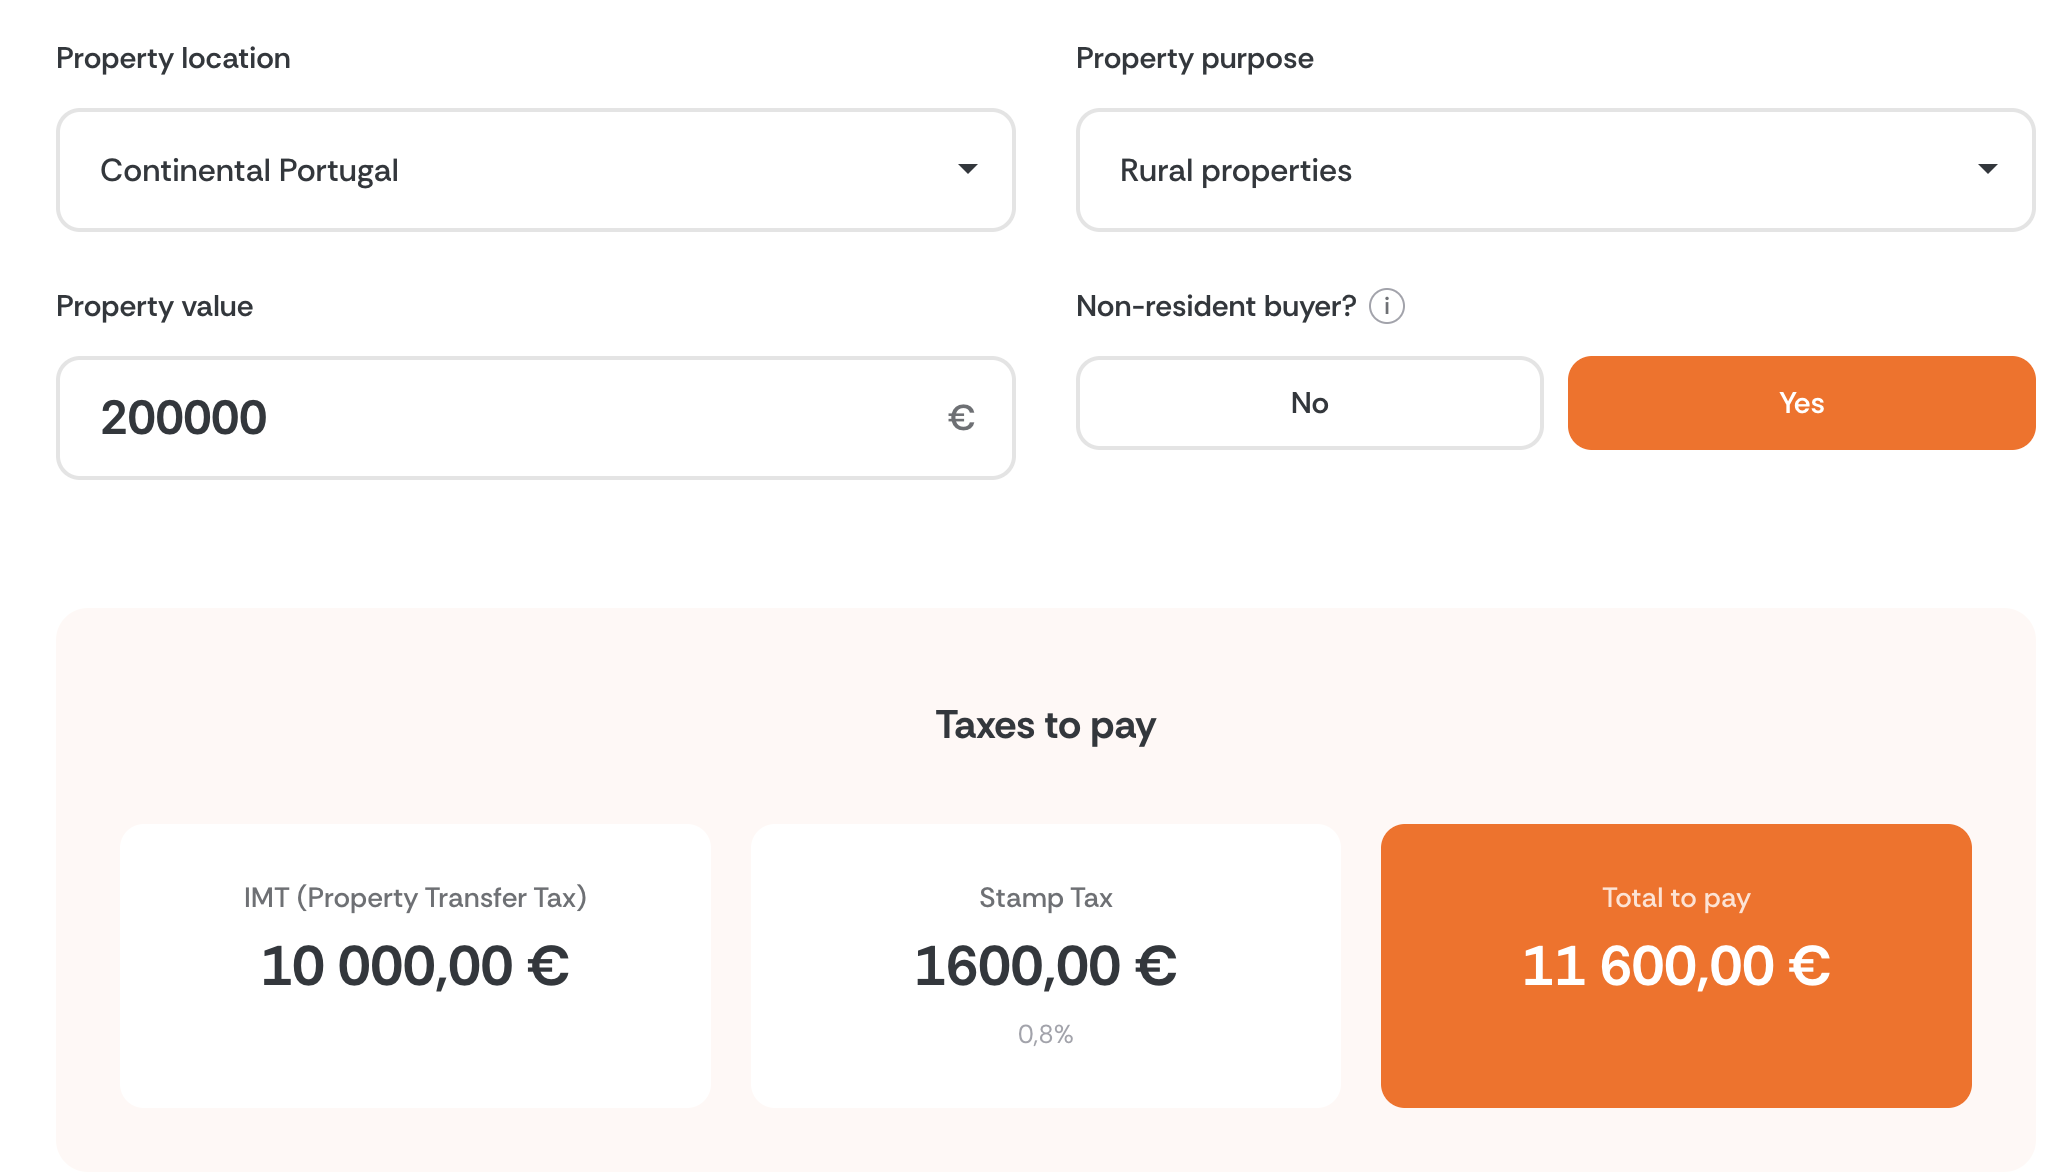
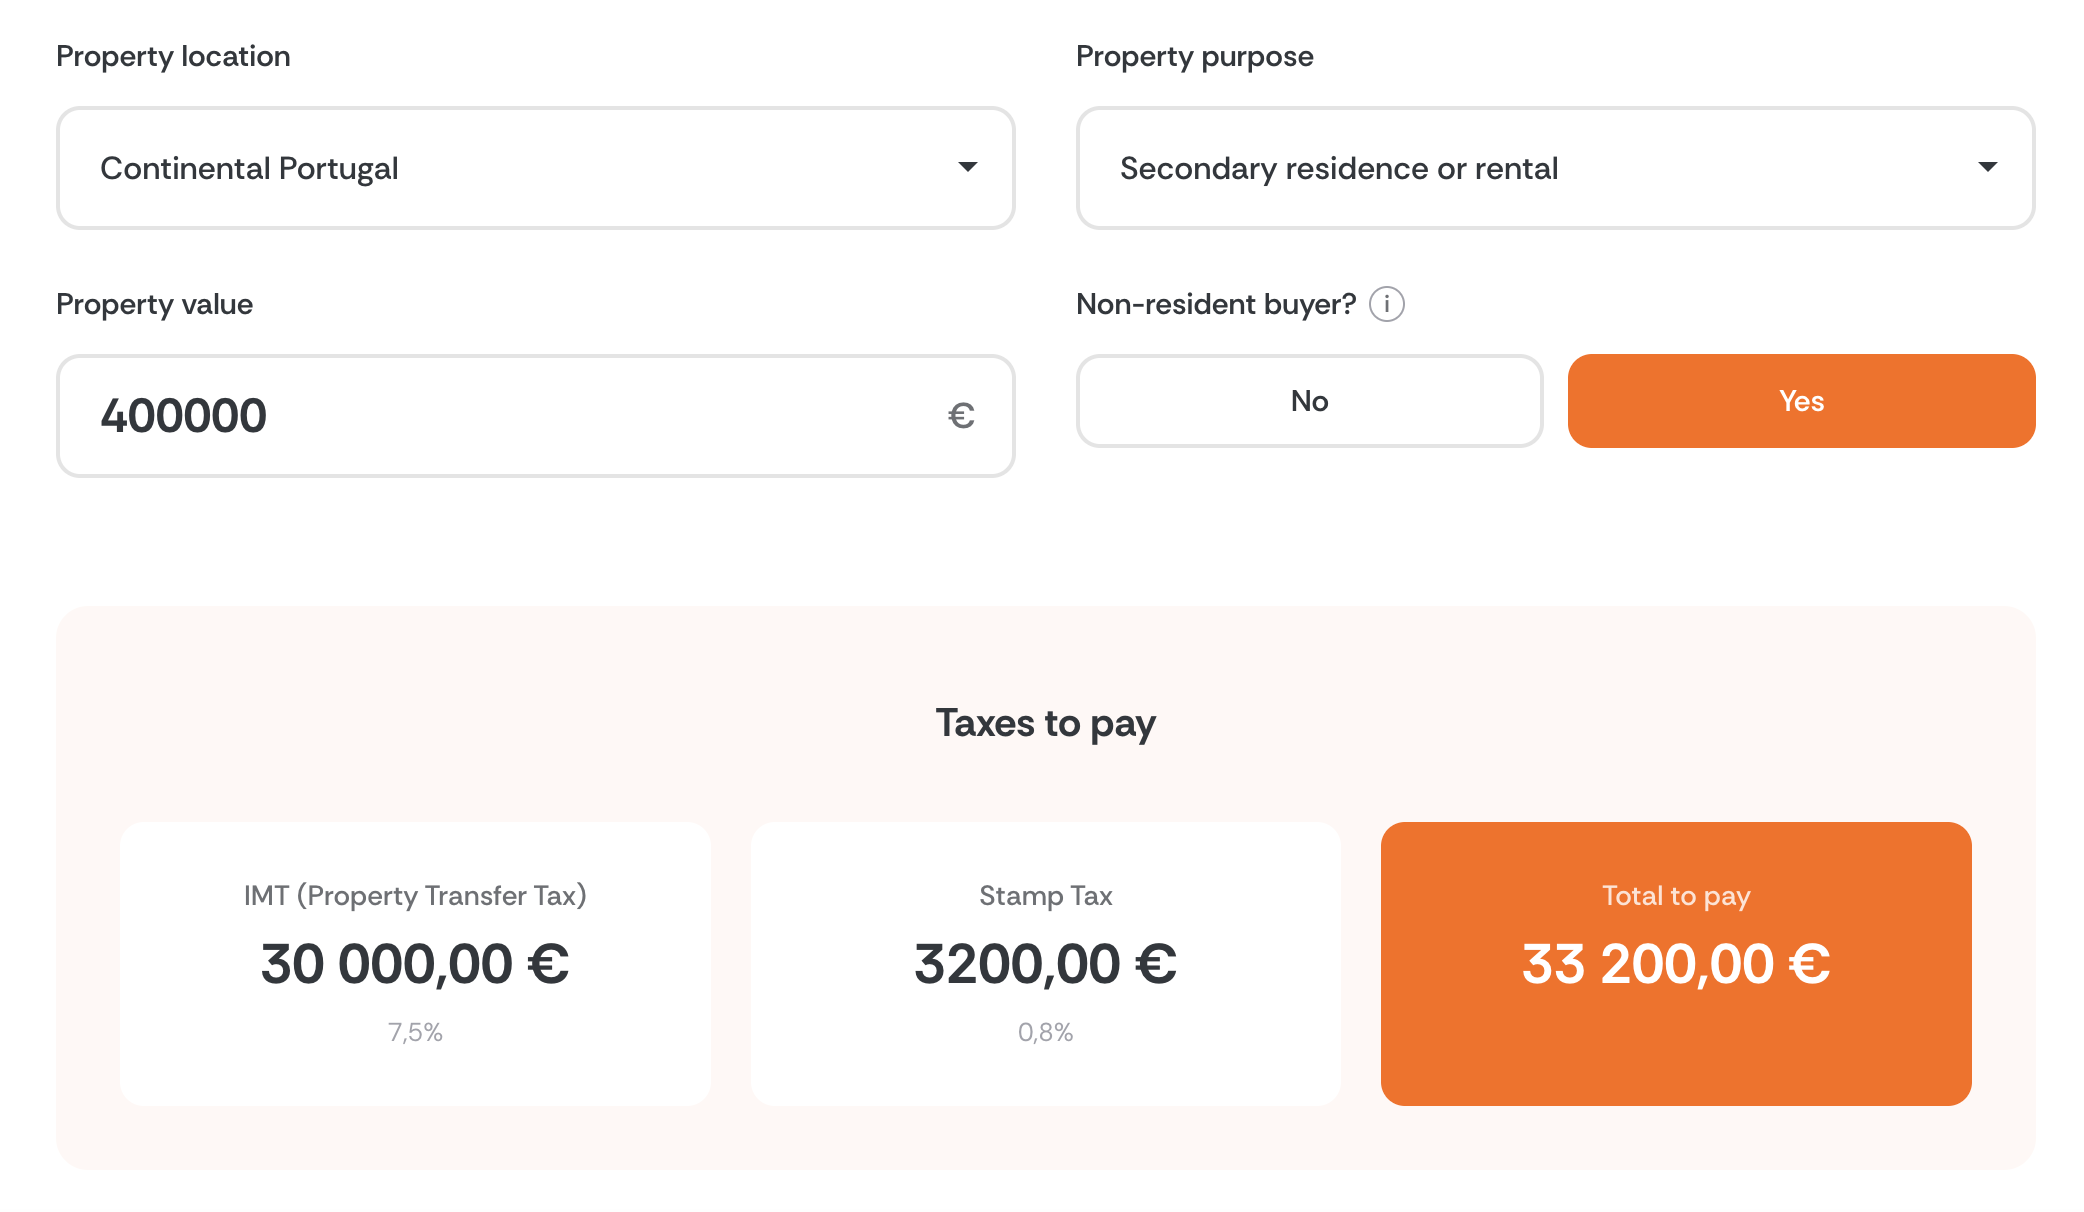
For the calculator scenario shown, a €200,000 rural-property purchase by a non-resident produces €10,000 IMT plus €1,600 purchase Stamp Duty, or €11,600 in taxes. Add approximately €2,000 for bank/notary costs. A separate calculator scenario for a completed €400,000 home bought by a non-resident shows €30,000 IMT plus €3,200 Stamp Duty, or €33,200 in taxes, plus approximately €2,000 in bank/notary costs. These examples use the stated purchase price; a higher VPT may change the taxable base. Loan Stamp Duty of 0.6% is due only if the purchase is financed, based on the loan amount. A construction permit commonly takes 6 months to 1 year, before the build itself. The 2026 licensing reform has removed the permit requirement for certain rebuilds of existing homes (what changed), and VAT on qualifying construction works stands at 6%.
For tax purposes, the official construction cost per m² used to calculate the property's taxable value is €570 per m² in 2026, well below market build costs (official reference).
Three routes, one decision:
- Buy land and build from scratch - full control, longest timeline.
- Buy land with approved plans - faster, less freedom.
- Buy off-plan from a developer - least risk, least customisation.
Budget a 10% to 20% contingency on any build, and expect banks to finance proportionally less on construction than on a completed home.
Common Pitfalls of Buying Property in Portugal
Most bad outcomes are predictable. Here are the mistakes we see repeat, and the numbers behind them.
The 10 Pitfalls That Cost Foreign Buyers the Most
- Buying before mortgage pre-approval. If the loan is refused after you pay the sinal, you either lose the 10% deposit or renegotiate from a weak position. Get approved first.
- Assuming a ruin can be rebuilt. A ruin is not automatically rebuildable, and a rebuild is usually limited to the original footprint and volume. New residential construction on rustic land is generally prohibited, whatever the seller says.
- Buying with undeclared floor area or additions. A bank may exclude an unregistered floor, extension, attic conversion or pool from its valuation. If the eligible valuation is below the price, 80% LTV and 80% LTC caps can reduce the mortgage and increase the buyer’s contribution. Check the declared area against the land registry, tax record, use licence and approved plans; confirm that any extensions are properly licensed.
- Not checking title, boundaries and access rights. Verify ownership and legal parcel boundaries, registered easements, rights of way and lawful road access. These checks reveal restrictions on access or use that a floor-area comparison will not catch.
- Missing RAN/REN overlays. Agricultural and ecological reserve classifications can block renovation or extension on land that looks perfectly buildable.
- Inheriting condominium debts. Outstanding charges and approved building works pass with the property unless they are settled at the deed. Ask for the minutes of the last two years.
- Underestimating the tax bill. On a €300,000 urban residential purchase by a non-resident, IMT at 7.5% is €22,500 and purchase Stamp Duty at 0.8% is €2,400, before any loan Stamp Duty or closing costs. If the VPT is higher than the declared price, it may increase the taxable base.
- Believing that buying property buys residency. Portugal's Golden Visa stopped accepting real estate in October 2023. Property ownership grants no permit by itself.
- Ignoring the exchange rate. A 3% swing on a €500,000 purchase is €15,000. Non-euro buyers should plan the currency transfer before the deed date, not on the day.
- Buying to let short-term without checking the parish. In contained areas of Lisbon, a new Alojamento Local registration is refused. The property was bought for a business that cannot be licensed.
How to Avoid Them
- Get written confirmation from the municipality on what the land permits, before you make an offer.
- Consider independent legal advice early. A lawyer is optional in Portugal, but can check title, licences, debts, planning restrictions and the CPCV. Obtain a fee quote separately.
- Compare measured floor areas and every extension, attic conversion or pool with the land registry, tax record, use licence and approved plans; check the VPT before estimating IMT and purchase Stamp Duty.
- Appoint a fiscal representative or register for electronic notifications if you live outside the EU/EEA.
- Respect the 45% debt-to-income ceiling. Stretching it delays approval instead of raising it.
- If using a mortgage, include a clearly drafted suspensive clause for mortgage refusal in the CPCV. Do not assume a low valuation alone guarantees a refund.
- Check the Alojamento Local ratio of the parish before buying for short-term rental.
Red Flags in a Listing
- No energy certificate or use licence referenced in the ad.
- "Ruin, ready to rebuild" with no municipal document attached.
- Price per m² far below the local average - usually a legal defect, not a bargain.
- Seller pushing to skip the CPCV or the lawyer.
- A floor, extension, attic conversion or pool visible during the visit but missing from official property records or approved plans.
Beyond Property-Buying: Portugal Visas and Citizenship
Residency is a separate process from the purchase. Portugal offers several routes, and property ownership supports them rather than replacing them.
Golden Visa
The Golden Visa is still open, but real estate no longer qualifies - and neither do real estate funds. Since October 2023, the eligible routes include a €500,000 investment in a regulated venture capital fund with no property exposure, a €500,000 research donation, a €250,000 cultural heritage donation, or company creation with jobs (2026 programme). It remains the only route that does not require physical residence in the country.
D2 and D8 Visas: Entrepreneurs and Remote Workers
The D2 visa targets entrepreneurs and company founders. It requires a credible business plan and evidence of means, but no predefined minimum investment.
The D8 digital nomad visa targets remote employees and freelancers. The income threshold rose in 2026 to €3,680 per month - four times the national minimum wage of €920 (2026 threshold), with increases for family members.
D7 Visa
The D7 visa is for people with regular passive income only, such as pensions, dividends, royalties or rental income. Remote employment belongs under the D8 route, not D7. The 2026 D7 requirement is €920 per month for the main applicant (€11,040 per year), plus 50% for a spouse and 30% per dependent child (D7 requirements).
Applicants must show accommodation in Portugal. This is where buying a property directly helps: a registered address supports a D7 or D8 application.
Does Buying Property in Portugal Give You Residency or Citizenship?
No - and this is the single most expensive misunderstanding in the market.
- Buying property in Portugal does not grant a residence permit. You need a visa route: D7, D8, D2 or the Golden Visa through funds.
- Owning a home strengthens an application. It evidences accommodation and ties to the country, which D7 and D8 files require.
- Citizenship comes after years of legal residence, not after a purchase. Since the nationality law change of May 2026, naturalisation requires 7 years of residence for EU and CPLP nationals and 10 years for other nationalities, replacing the previous 5-year rule (citizenship timeline).
- NHR is closed. Newcomers should be assessed for IFICI instead, and only if their activity qualifies.
If your goal is European residency or citizenship, structure the visa first and the property second.
Conclusion
The Portuguese market is still rising - +16.5% in a year to June 2026 - but it is rising more slowly than in 2024. For a foreign buyer, the decisive changes in 2026 are fiscal, not cyclical: the flat 7.5% IMT for non-residents, the closing of NHR, and the extension of citizenship timelines.
Three things you can control: prepare financing before the search, budget 4% to 10% of the purchase price for taxes and closing costs (excluding the deposit and optional lawyer), and verify the property’s legal status and VPT before signing.
CAFIMO negotiates across 15+ banking partners, and the service is free for the client. Whether you buy from abroad or after a visit, you get one point of contact, a written comparison of offers and a schedule you can plan around.
Request your simulation and talk to our brokers.
Frequently Asked Questions About Buying Property in Portugal
Can foreigners buy property in Portugal?
Yes. Any nationality can buy property in Portugal; there is no ownership restriction, minimum investment or requirement to live in the country. You need a Portuguese tax number (NIF). A Portuguese bank account is commonly useful, especially for mortgage financing, but it is not a universal requirement for a cash purchase. A lawyer is optional but recommended for due diligence. Tax residency, property use and financing affect the taxes: non-residents pay a flat 7.5% IMT on urban residential property from May 2026, subject to the legal cancellation conditions.
How much does it cost to buy a house in Portugal in 2026?
Budget roughly 4% to 10% of the purchase price for acquisition taxes and closing costs, excluding the down payment and optional lawyer. For the €200,000 scenarios above, the resident’s taxes are €5,142.04 and the non-resident’s are €16,600; add approximately €2,000 in bank/notary costs. If there is a mortgage, add loan Stamp Duty of 0.6% of the loan amount. The total-funds figures include the deposit paid at the CPCV, so do not add that deposit a second time at the deed.
Can I get a mortgage in Portugal as a non-resident?
Yes. Many banks lend up to 80% LTV to non-residents, while some situations are capped at 70%. Non-resident mortgage terms are generally limited to 30 years. Debt-to-income is generally capped at 45%. For variable-rate loans, banks add a spread, typically 0.5% to 1%, to 6- or 12-month Euribor. Fixed rates are priced separately and are often based on average government bond yields. Your offer depends on the borrower and bank.
Do I need to live in Portugal to buy property there?
No. You can buy, finance, rent out and sell Portuguese property without being resident. You need a NIF; a Portuguese bank account is commonly useful for mortgage payments but is not a universal condition for a cash purchase. If you live outside the EU/EEA, you generally need a tax representative unless you register for official electronic notifications (gov.pt purchase guide).
Does buying property in Portugal give you residency or citizenship?
No. Buying a property does not grant a residence permit. The Golden Visa route described in this guide no longer accepts real-estate purchases. Residency depends on a qualifying visa route; ownership can help evidence accommodation for D7 or D8 applications. Citizenship follows years of legal residence: 7 years for EU and CPLP nationals, and 10 years for other nationalities under the 2026 law.
Do non-residents pay more IMT in 2026?
Yes. From 25 May 2026, non-residents pay a flat 7.5% IMT on urban residential property, subject to statutory cancellation conditions. Tax residency, not nationality, determines this treatment. The taxable basis is generally the higher of the deed/contract value and the VPT. A VPT above the price is uncommon in a normal arm’s-length sale; the calculator examples use the stated purchase prices.
Is the NHR tax regime still available in 2026?
No. The Non-Habitual Resident regime is closed to new applicants since 2024. It was replaced by IFICI, which offers a 20% flat rate on qualifying Portuguese income and, in many cases, exemption on foreign income for 10 years - restricted to research, innovation and other designated high-value activities.
How long does it take to buy a house in Portugal?
Plan for two to four months from accepted offer to deed. When bank financing is involved, allow around 45–60 days from mortgage application to deed. Timing depends on document readiness, valuation, bank processing and notary availability.
Useful Sources
- Official guidance on the IMT and Stamp Duty taxable base - Portal das Finanças
- Official purchase and sale guide - gov.pt
- Fire insurance rules - ASF
- INE house price data, Q2 2026 - eco.sapo.pt
- Non-resident IMT rules and exemptions - imtcalc.pt
- Housing tax package, Decree-Law 97/2026 - portaldasfinancas.gov.pt
- IMI and AIMI 2026 - pwc.pt
- IFICI regime - portugal-business.com
- Golden Visa 2026 - theportugalnews.com
- Rental yields 2026 - idealista.pt